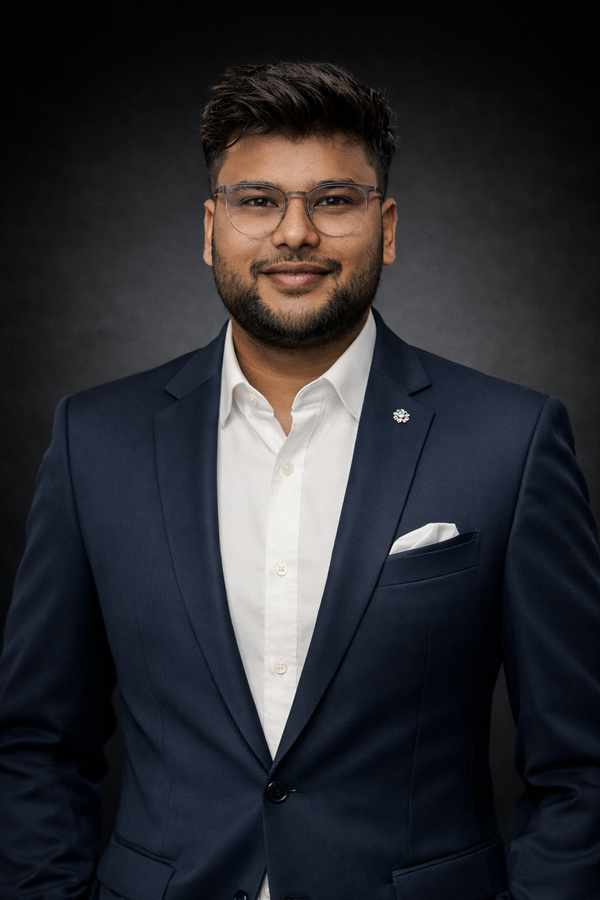
Mayank Bansal is a CFA Charterholder and heads the Equity Research team at Kapitales Research, with over 5 years of experience analysing global equity markets. He leads fundamental, data-driven research combining rigorous financial analysis with macro trends.
Kapitales Morning Highlights from Wall Street to ASX - 10 November 2026
Source: Kapitales Research
Headline
ASX 200 futures point to a strong opening, rising 93 points (+1.02%) following Wall Street’s rally.
Wall Street rallied sharply, with the S&P 500 and Nasdaq recording their strongest sessions since April.
Chipmakers rebounded, supporting a recovery in technology stocks following last week's AI-driven sell-off.
Oil prices declined further amid hopes of diplomatic progress in the US–Iran conflict.
US inflation remained in focus ahead of Tuesday's CPI release, while China's factory-gate inflation reached a four-year high.
Global Markets Overview
Index
Level
Change
S&P 500
7,550.00
+2.35%
Nasdaq Composite
25,253.00
+2.74%
Dow Jones
52,390.00
+2.15%
FTSE 100
10,783.00
+1.02%
S&P/TSX Composite
36,446.00
+1.84%
NZX 50
13,974.00
-0.18%
Nikkei (Japan)
58,776.00
+2.33%
India
81,107.00
+0.13%
Global equity markets delivered a broadly positive performance, supported by improving investor sentiment, renewed buying interest in technology stocks and easing concerns over geopolitical developments. In the United States, the S&P 500, Nasdaq Composite and Dow Jones Industrial Average advanced strongly, reflecting a widespread recovery across major sectors. Technology shares led the rebound as investors returned to semiconductor and artificial intelligence companies following recent selling pressure. European markets also strengthened, with the UK's FTSE 100 gaining ground amid improved risk appetite. Canada's S&P/TSX Composite recorded solid gains, supported by broader market optimism.
Across Asian markets, Japan's Nikkei posted a strong advance as investors increased exposure to equities, while India's benchmark index registered a modest improvement, indicating relatively cautious trading activity. New Zealand's NZX 50 declined slightly, contrasting with the positive momentum across most international markets. Overall, global equities reflected renewed investor confidence, although upcoming US inflation data, monetary policy expectations and geopolitical uncertainty remained important factors influencing market direction and near-term investment decisions across major financial markets worldwide.
Commodities & Crypto
Asset
Price (US$)
Change
Gold
4,142.38/oz
+1.77%
WTI Crude
87.05/bbl
-4.16%
Copper
6.36/lb
+2.27%
Uranium
4,570.92
+5.91%
Silver
53.45/oz
+3.48%
Bitcoin
74,864.00
+1.11%
Commodity markets recorded predominantly positive movements, with gold, silver, copper and the uranium benchmark advancing, while crude oil declined sharply. Gold prices rose as precious metals attracted renewed buying interest, while silver registered stronger gains, outperforming gold during the session. Copper also advanced, reflecting positive price momentum across industrial metals. Uranium prices recorded a substantial increase, outperforming other major commodities during the session. Meanwhile, WTI crude oil fell significantly as investors assessed the possibility of diplomatic progress in the US–Iran conflict and its implications for global energy supplies. In the cryptocurrency market, Bitcoin moved higher, indicating renewed buying interest in digital assets.
Bond Yields
Indicator
Yield
Change
Australia 10-Year Bond Yield
5.005%
-0.019 bps
Japan 10-Year Bond Yield
2.665%
+0.033 bps
US 10-Year Bond Yield
4.886%
+0.030 bps
US 30-Year Bond Yield
5.275%
+0.015 bps
Global bond markets displayed divergent movements as investors assessed inflation expectations, monetary policy developments and broader economic conditions. Australia's 10-year government bond yield declined to 5.005%, reflecting a modest easing in domestic borrowing costs. In contrast, Japan's 10-year government bond yield increased to 2.665%, indicating upward pressure on Japanese government bond yields. Meanwhile, US Treasury yields moved higher across longer maturities, with the 10-year yield rising to 4.886% and the 30-year yield advancing to 5.275%. The increase in US yields suggested continued pressure on government bond prices as investors positioned ahead of upcoming inflation data and reassessed the outlook for Federal Reserve monetary policy. Overall, Australian bond yields edged lower, while Japanese and US government bond yields strengthened, highlighting differing movements across major sovereign debt markets. Investors remained focused on inflation trends, central bank policy expectations and economic developments that could influence bond market volatility and future borrowing costs.
Key Drivers
US equities rallied strongly, with the Nasdaq recording its best session since April.
Market breadth strengthened, with advancing stocks outnumbering declining stocks by more than 3:1.
Copper rebounded to US$6.30/lb after touching a 17-week low last week.
The iShares Semiconductor ETF surged over 7%, recovering from last week's approximately 13% decline.
Broadcom shares jumped 9%, supported by renewed semiconductor buying.
Nvidia declined 4.2%, recovering from an intraday drop of 8.7% amid a board investigation.
AMD surged 13% following an Oppenheimer upgrade to Outperform, with a US$600 price target.
Oppenheimer projected AMD's data centre revenue growth at 135% in 2027.
Tesla advanced 5.5%, while Amazon gained 3% and Alphabet rose approximately 1%.
Citi downgraded US equities and global technology stocks to neutral from overweight.
Citi upgraded European equities excluding the UK to overweight.
Goldman Sachs projected US 10-year Treasury yields could stabilise between 4.75% and 5.00%.
Gulf merger and acquisition activity declined to approximately US$5 billion from US$69 billion a year earlier.
Brent crude dropped approximately 5%, falling below US$93 per barrel amid diplomatic optimism.
Trump met Qatar's prime minister to discuss a potential Iran ceasefire and renewed nuclear negotiations.
US Congressional Democrats considered using the 11 December government funding deadline to pressure Trump over Iran.
Federal Reserve official Austan Goolsbee highlighted persistent inflation risks and potential overheating from AI investment.
China's producer prices increased 5.7% year-on-year in October, exceeding expectations of 5.3%.
China's consumer inflation slowed to 0.7% in October from 0.9%, while core inflation eased to 0.8%.
ASX Company News
Superloop Limited (ASX: SLC) announced on 10 November 2026 a positive trading update for the first four months of FY2027, with total customers increasing by 18,500 to 954,000 as of 31 October 2026. Consumer customers increased by 23,000, while the Business segment added 2,300 customers. The company forecast FY2027 underlying EBITDA of AU$148–156 million, representing growth of 21–27% compared with FY2026. Capital expenditure is expected to reach AU$58–62 million, reflecting increased investment in Smart Communities and integration activities.
Life360, Inc. (ASX: 360) announced its third-quarter financial results on 9 November 2026, reporting a 40% year-on-year increase in revenue to US$174.1 million. Net income rose 130% to US$22.5 million, while adjusted EBITDA increased 41% to US$34.6 million. Global monthly active users reached 107.7 million, supported by 5.3 million quarterly additions. The company revised its FY2026 revenue guidance to US$665–681 million and narrowed its adjusted EBITDA forecast to US$132–138 million.
Monadelphous Group Limited (ASX: MND) announced on 10 November 2026 an encouraging business update, supported by strong engineering construction activity and new contract awards. The company secured approximately AU$830 million in additional contracts since 1 July 2026, maintaining elevated operational activity. Monadelphous forecast revenue of approximately AU$1.7 billion for the six months ending 31 December 2026, alongside net profit after tax of AU$80–85 million. However, operating activity is expected to moderate during the second half of FY2027 as existing projects approach completion.
Vulcan Energy Resources Limited (ASX: VUL) announced on 10 November 2026 the mobilisation of its second heavy-duty drilling rig at the Lionheart lithium project in Germany, supporting accelerated construction and well development. The company has invested approximately AU$82 million in two drilling rigs, strengthening operational control over its planned 28-well program. With seven production and reinjection wells already established, Lionheart targets annual production of 24,000 tonnes of lithium hydroxide monohydrate, with first production scheduled for the second half of 2028.
Brightstar Resources Limited (ASX: BTR) announced on 10 November 2026 continued construction progress at its Goldfields Project in Western Australia, maintaining its June 2027 first-gold production target. Engineering, procurement and construction progress reached 50%, while engineering activities achieved 90% completion. The company's Laverton processing plant is designed for annual throughput of 1.5 million tonnes. Brightstar also acquired the 223-room Boomers Mining Accommodation Camp to support workforce requirements and secured an AU$82 million placement in October to accelerate development activities at its Sandstone Project. Construction remains on schedule and within budget.
Key Economic Drivers (What to Watch Today)
10:30 AM AEDT – Australia: Consumer Confidence release, providing insights into household sentiment and spending expectations.
11:30 AM AEDT – Australia: Business Confidence data, highlighting business conditions, investment sentiment and economic outlook.
2:00 PM AEDT – China: Balance of Trade release, offering insights into export and import activity and global trade demand.
12:30 AM AEDT (Next Day) – United States: Inflation Rate (CPI) release, providing insights into consumer price pressures and Federal Reserve interest rate expectations.
Summary
ASX 200 futures indicate a strong opening, rising 93 points (+1.02%) as Wall Street rallied on a semiconductor rebound and easing US–Iran tensions.
The Dow Jones advanced 2.15%, supported by broad-based buying across US equities.
Semiconductor stocks rebounded sharply, with the iShares Semiconductor ETF gaining over 7%.
AMD surged 13%, while Broadcom advanced 9%, leading the technology sector's recovery.
Nvidia declined 4.2% amid reports of an independent board investigation.
European and Canadian equities strengthened, with the FTSE 100 gaining 1.02% and S&P/TSX Composite rising 1.84%.
Gold advanced 1.77% to US$4,142.38/oz, while silver surged 3.48% to US$53.45/oz.
WTI crude declined 4.16% to US$87.05/bbl amid hopes of diplomatic progress in the US–Iran conflict.
China's producer inflation accelerated to 5.7% year-on-year, while consumer inflation slowed to 0.7%; upcoming US CPI data remained a key market focus.
Disclaimer for Kapitales Research
The materials provided by Kapitales Research, including articles, news, data, reports, opinions, images, charts, and videos ("Content"), are intended for personal, non-commercial use only. The primary goal of this Content is to educate and inform readers. This Content is not meant to offer financial advice, nor does it include any recommendation or opinion that should be relied upon for making financial decisions. Certain Content on this platform may be sponsored or unsponsored, but it does not serve as a solicitation or endorsement to buy, sell, or hold any securities, nor does it encourage any specific investment activities. Kapitales Research is not authorized to provide investment advice, and we strongly advise users to seek guidance from a qualified financial professional, such as a financial advisor or stockbroker, before making any investment choices. Kapitales Research disclaims all liability for any direct, indirect, incidental, or consequential damages arising from the use of the Content, which is provided without any warranties. The opinions expressed by contributors or guests are their own and do not necessarily reflect the views of Kapitales Research. Media such as images or music used on this platform are either owned by Kapitales Research, sourced through paid subscriptions, or believed to be in the public domain. We have made reasonable efforts to credit sources where appropriate. Kapitales Research does not claim ownership of any third-party media unless explicitly stated otherwise.
Customer Notice:
Nextgen Global Services Pty Ltd trading as Kapitales Research (ABN 89 652 632 561) is a Corporate Authorised Representative (CAR No. 1293674) of Enva Australia Pty Ltd (AFSL 424494). The information contained in this website is general information only. Any advice is general advice only. No consideration has been given or will be given to the individual investment objectives, financial situation or needs of any particular person. The decision to invest or trade and the method selected is a personal decision and involves an inherent level of risk, and you must undertake your own investigations and obtain your own advice regarding the suitability of this product for your circumstances. Please be aware that all trading activity is subject to both profit & loss and may not be suitable for you. The past performance of this product is not and should not be taken as an indication of future performance.
Disclosure: The information mentioned above has been sourced from the company reports and a third-party database, i.e. Koyfin. Investors are advised to use strict stop-loss to protect their investments in case of any unfavorable/uncertain market events.
Kapitales Research, Level 13, Suite 1A, 465 Victoria Ave, Chatswood, NSW 2067, Australia | 1800 005 780 | info@kapitales.com.au
We use cookies to help us improve, promote, and protect our services.
By continuing to use this site, we assume you consent to this.
Read our
Privacy Policy
and
Terms & Conditions
Kapitales Morning Highlights from Wall Street to ASX - 10 November 2026
Headline
Global Markets Overview
Global equity markets delivered a broadly positive performance, supported by improving investor sentiment, renewed buying interest in technology stocks and easing concerns over geopolitical developments. In the United States, the S&P 500, Nasdaq Composite and Dow Jones Industrial Average advanced strongly, reflecting a widespread recovery across major sectors. Technology shares led the rebound as investors returned to semiconductor and artificial intelligence companies following recent selling pressure. European markets also strengthened, with the UK's FTSE 100 gaining ground amid improved risk appetite. Canada's S&P/TSX Composite recorded solid gains, supported by broader market optimism.
Across Asian markets, Japan's Nikkei posted a strong advance as investors increased exposure to equities, while India's benchmark index registered a modest improvement, indicating relatively cautious trading activity. New Zealand's NZX 50 declined slightly, contrasting with the positive momentum across most international markets. Overall, global equities reflected renewed investor confidence, although upcoming US inflation data, monetary policy expectations and geopolitical uncertainty remained important factors influencing market direction and near-term investment decisions across major financial markets worldwide.
Commodities & Crypto
Commodity markets recorded predominantly positive movements, with gold, silver, copper and the uranium benchmark advancing, while crude oil declined sharply. Gold prices rose as precious metals attracted renewed buying interest, while silver registered stronger gains, outperforming gold during the session. Copper also advanced, reflecting positive price momentum across industrial metals. Uranium prices recorded a substantial increase, outperforming other major commodities during the session. Meanwhile, WTI crude oil fell significantly as investors assessed the possibility of diplomatic progress in the US–Iran conflict and its implications for global energy supplies. In the cryptocurrency market, Bitcoin moved higher, indicating renewed buying interest in digital assets.
Bond Yields
Global bond markets displayed divergent movements as investors assessed inflation expectations, monetary policy developments and broader economic conditions. Australia's 10-year government bond yield declined to 5.005%, reflecting a modest easing in domestic borrowing costs. In contrast, Japan's 10-year government bond yield increased to 2.665%, indicating upward pressure on Japanese government bond yields. Meanwhile, US Treasury yields moved higher across longer maturities, with the 10-year yield rising to 4.886% and the 30-year yield advancing to 5.275%. The increase in US yields suggested continued pressure on government bond prices as investors positioned ahead of upcoming inflation data and reassessed the outlook for Federal Reserve monetary policy. Overall, Australian bond yields edged lower, while Japanese and US government bond yields strengthened, highlighting differing movements across major sovereign debt markets. Investors remained focused on inflation trends, central bank policy expectations and economic developments that could influence bond market volatility and future borrowing costs.
Key Drivers
ASX Company News
Key Economic Drivers (What to Watch Today)
Summary
Disclaimer for Kapitales Research
The materials provided by Kapitales Research, including articles, news, data, reports, opinions, images, charts, and videos ("Content"), are intended for personal, non-commercial use only. The primary goal of this Content is to educate and inform readers. This Content is not meant to offer financial advice, nor does it include any recommendation or opinion that should be relied upon for making financial decisions. Certain Content on this platform may be sponsored or unsponsored, but it does not serve as a solicitation or endorsement to buy, sell, or hold any securities, nor does it encourage any specific investment activities. Kapitales Research is not authorized to provide investment advice, and we strongly advise users to seek guidance from a qualified financial professional, such as a financial advisor or stockbroker, before making any investment choices. Kapitales Research disclaims all liability for any direct, indirect, incidental, or consequential damages arising from the use of the Content, which is provided without any warranties. The opinions expressed by contributors or guests are their own and do not necessarily reflect the views of Kapitales Research. Media such as images or music used on this platform are either owned by Kapitales Research, sourced through paid subscriptions, or believed to be in the public domain. We have made reasonable efforts to credit sources where appropriate. Kapitales Research does not claim ownership of any third-party media unless explicitly stated otherwise.
Customer Notice:
Nextgen Global Services Pty Ltd trading as Kapitales Research (ABN 89 652 632 561) is a Corporate Authorised Representative (CAR No. 1293674) of Enva Australia Pty Ltd (AFSL 424494). The information contained in this website is general information only. Any advice is general advice only. No consideration has been given or will be given to the individual investment objectives, financial situation or needs of any particular person. The decision to invest or trade and the method selected is a personal decision and involves an inherent level of risk, and you must undertake your own investigations and obtain your own advice regarding the suitability of this product for your circumstances. Please be aware that all trading activity is subject to both profit & loss and may not be suitable for you. The past performance of this product is not and should not be taken as an indication of future performance.
Disclosure: The information mentioned above has been sourced from the company reports and a third-party database, i.e. Koyfin. Investors are advised to use strict stop-loss to protect their investments in case of any unfavorable/uncertain market events.
Kapitales Research, Level 13, Suite 1A, 465 Victoria Ave, Chatswood, NSW 2067, Australia | 1800 005 780 | info@kapitales.com.au