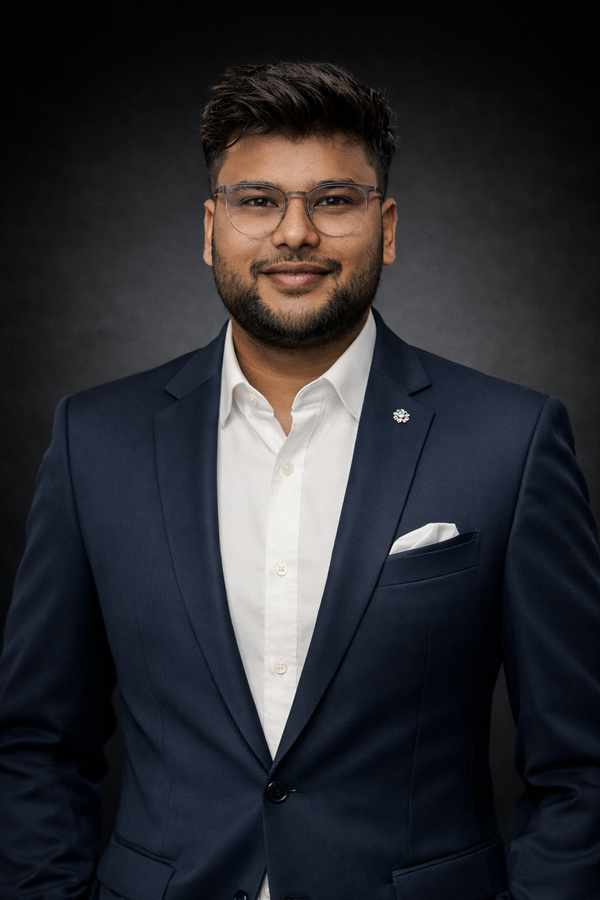
Mayank Bansal is a CFA Charterholder and heads the Equity Research team at Kapitales Research, with over 5 years of experience analysing global equity markets. He leads fundamental, data-driven research combining rigorous financial analysis with macro trends.
Markets Today (30 October 2026) at Open: Kapitales Morning Highlights from Wall Street to ASX
Source: Kapitales Research
Headline
ASX 200 futures point to a positive opening, rising 32 points (+0.35%).
S&P 500 and Nasdaq ended their three-session winning streak amid technology-sector selling.
Alphabet shares plunged 12.6%, pressured by disappointing search performance and AI spending concerns.
US 10-year Treasury yields declined below 5% as demand for government bonds strengthened.
Defensive stocks and small-cap companies outperformed amid broader market rotation.
December Fed rate-hike expectations eased to 76% following in-line US PCE inflation and stronger-than-expected Q3 GDP growth.
The ECB held interest rates steady as investors assessed the monetary policy outlook.
Global Markets Overview
Index
Level
Change
S&P 500
7,720.00
-0.30%
Nasdaq Composite
26,185.00
-1.38%
Dow Jones
52,343.00
-0.25%
FTSE 100
10,722.00
+0.26%
S&P/TSX Composite
36,249.00
-0.04%
NZX 50
13,710.00
+0.14%
Nikkei (Japan)
64,659.00
+1.10%
India
74,151.00
+1.24%
Global equity markets delivered a mixed performance, reflecting divergent investor sentiment across major regions. In the United States, the S&P 500, Nasdaq Composite and Dow Jones Industrial Average closed lower, as selling pressure in technology stocks weighed on broader market sentiment. The Nasdaq experienced the sharpest decline among major US benchmarks, highlighting continued concerns surrounding technology valuations and corporate earnings. Meanwhile, European equities showed resilience, with the UK's FTSE 100 advancing despite ongoing economic uncertainty and shifting monetary policy expectations. Canada's S&P/TSX Composite finished marginally lower, indicating subdued investor participation.
Across Asian markets, Japan's Nikkei recorded solid gains, supported by positive investor sentiment and strength in domestic equities. Indian equities also advanced, reflecting improved market confidence and buying interest across key sectors. New Zealand's NZX 50 ended higher, indicating a relatively positive trading session. Overall, global markets demonstrated contrasting trends, with weakness in US technology shares offset by gains across selected European and Asian benchmarks, while investors continued assessing corporate earnings, economic developments and monetary policy expectations.
Commodities & Crypto
Asset
Price (US$)
Change
Gold
4,021.33/oz
-1.14%
WTI Crude
102.92/bbl
+0.13%
Copper
6.56/lb
-1.25%
Uranium
4,813.21
-1.45%
Silver
52.25/oz
-2.64%
Bitcoin
78,926.00
-2.88%
Commodity markets displayed a predominantly weaker trend, reflecting cautious investor sentiment amid global economic uncertainty and shifting monetary policy expectations. Gold prices declined amid selling pressure across precious metals. Silver experienced a sharper decline, highlighting broader selling pressure across precious metals. Meanwhile, copper prices weakened, reflecting concerns surrounding industrial demand and the outlook for global manufacturing activity. Uranium prices also declined, reflecting broader weakness across commodity markets. In contrast, West Texas Intermediate (WTI) crude oil edged higher, demonstrating relative resilience amid ongoing geopolitical uncertainty and supply-related considerations. In the cryptocurrency market, Bitcoin declined considerably, reflecting reduced appetite for speculative assets amid broader financial market volatility. Overall, commodity and cryptocurrency markets remained under pressure, with modest strength in crude oil providing a limited offset to widespread declines across metals and digital assets.
Bond Yields
Indicator
Yield
Change
Australia 10-Year Bond Yield
5.131%
-0.050 bps
Japan 10-Year Bond Yield
2.842%
+0.016 bps
US 10-Year Bond Yield
4.925%
-0.059 bps
US 30-Year Bond Yield
5.298%
-0.031 bps
Global government bond yields moved predominantly lower, with Australian and US yields declining, while Japanese yields edged higher amid diverging monetary policy expectations. Australian 10-year government bond yields declined, reflecting improved demand for fixed-income securities amid changing interest rate expectations. In contrast, Japan's 10-year government bond yield edged higher, indicating continued upward pressure on domestic borrowing costs. Meanwhile, US Treasury yields declined across longer maturities, with the 10-year yield falling below 5% and the 30-year yield also moving lower. Shifting expectations regarding the Federal Reserve's future interest rate decisions also influenced bond market sentiment. Overall, government bond yields moved predominantly lower, with Australian and US yields declining while Japanese yields edged higher, reflecting differences in regional monetary policy expectations and prevailing market conditions.
Key Drivers
US equities closed lower as Alphabet's 12.6% plunge intensified concerns over AI investment returns.
Alphabet suffered an approximately US$500 billion market value wipeout following disappointing quarterly results.
Alphabet's Q3 revenue increased 25% to US$127.6 billion, while free cash flow turned negative at US$9 billion.
Fortinet and ServiceNow shares each plunged more than 20% following their quarterly earnings announcements.
S&P 500 Equal Weight Index gained 1.2%, supported by healthcare, real estate and financial stocks.
US 10-year Treasury yields fell 6 basis points to 4.9%, their lowest since 23 September.
US 2-year Treasury yields declined 8 basis points to 4.6%.
Brent crude approached US$116 per barrel, while WTI traded near US$102 amid Middle East supply concerns.
Microsoft reportedly planned a US$25 billion bond offering to support its expanding AI infrastructure investments.
Amazon reported Q3 revenue of US$201.9 billion, while shares declined approximately 7% in after-hours trading.
Eli Lilly's Q3 revenue surged 39% to US$24.4 billion, supported by strong Mounjaro sales.
Intel reported Q3 revenue of US$16.5 billion, but disappointing Q4 guidance pressured its shares.
Caterpillar reported Q3 revenue of US$20.68 billion, although its outlook disappointed investors.
The ECB maintained its deposit rate at 2.50%, while signalling readiness to respond to inflationary pressures.
US Q3 GDP expanded at an annualised 3.4%, exceeding expectations of 3.1%.
US September PCE inflation reached 3.6% annually, while core PCE increased 3.1%, matching expectations.
ASX Company News
Resmed Inc. (ASX: RMD) announced its first-quarter FY27 financial results on 29 October 2026. Revenue increased 6% to US$1.415 billion, supported by demand for sleep devices, masks and accessories. Net income rose 20% to US$418 million, while diluted earnings per share increased 23% to US$2.92. Non-GAAP gross margin improved to 62.5%, although operating cash flow declined 8% to US$422 million. The company returned more than US$1.0 billion to shareholders through dividends and share repurchases. Looking ahead, Resmed maintained FY27 revenue guidance of US$5.75–5.85 billion and non-GAAP diluted EPS guidance of US$12.00–12.25, while focusing on digital health innovation and expanding its sleep and breathing health businesses.
Helia Group Limited (ASX: HLI) released its third-quarter 2026 trading update on 30 October 2026. For the nine months ended September 2026, gross written premium declined to AU$82.5 million, compared to AU$176.0 million in the prior corresponding period. Insurance revenue decreased to AU$253.4 million from AU$274.9 million, while statutory net profit after tax fell to AU$136.5 million from AU$200.9 million. The decline reflected the loss of the Commonwealth Bank contract, expansion of the government's deposit scheme and weaker housing market activity. Meanwhile, the prescribed capital amount coverage ratio improved to 2.01 times, remaining above the company's target range. Looking ahead, Helia maintained FY26 insurance revenue guidance of AU$330–360 million, while monitoring housing market conditions, mortgage arrears and claims performance.
Coles Group Limited (ASX: COL) released its FY27 first-quarter sales results on 30 October 2026. Group sales revenue increased 2.2% to AU$11.209 billion, compared to AU$10.963 billion in the prior corresponding period. Supermarkets revenue advanced 3.6% to AU$10.320 billion, supported by eCommerce growth of 22.9%, while comparable supermarket sales increased 2.7%. However, Liquor revenue declined 1.3% to AU$831 million amid continued competitive pressures. The company opened eight supermarkets during the quarter and continued investing in digital capabilities, store improvements and customer value initiatives. Looking ahead, Coles expects first-half Supermarkets EBIT, excluding significant items, to remain broadly in line with the prior corresponding period, reflecting increased promotional investment, moderating sales growth and higher fuel-related costs.
Civmec Limited (ASX: CVL) announced its first-quarter FY27 operational and financial update on 29 October 2026. Revenue surged approximately 70% to AU$324 million, compared to AU$190.4 million in the prior corresponding period, supported by increased construction activity. EBITDA reached AU$35.1 million, representing a margin of 10.8%, while net profit after tax increased approximately 75% to AU$18.4 million. The company's order book stood at approximately AU$1.4 billion, supported by new contracts and extensions exceeding AU$220 million announced earlier in October. Civmec also secured the Wagerup Gallium project construction contract and progressed major defence, infrastructure and resources projects. Looking ahead, the company remains focused on executing its order book, expanding its workforce and pursuing opportunities across critical minerals, energy, infrastructure and defence.
Capstone Copper Corp. (ASX: CSC) released its financial performance report for the third quarter of 2026 on 29 October 2026. Revenue increased approximately 19% to US$712.0 million, compared to US$598.4 million in the prior corresponding period, supported by stronger realised copper prices. Adjusted EBITDA rose to a record US$358.3 million from US$249.2 million, while net income attributable to shareholders declined to US$98.5 million from US$248.1 million. Copper production decreased approximately 18% to 45,218 tonnes, reflecting operational disruptions and lower production at selected mines. Meanwhile, net debt declined to US$564.0 million, with available liquidity reaching US$1.089 billion. Looking ahead, Capstone expects FY26 copper production near the lower end of its 200,000–230,000-tonne guidance range, while prioritising operational improvements, the Mantoverde expansion and balance sheet strengthening.
Stocks trading ex-dividend today
Stanmore Resources Limited (ASX: SMR) – AU$0.031
Key Economic Drivers (What to Watch Today)
11:30 AM AEDT – Australia Producer Price Index (PPI): Provides insights into producer-level inflation and potential cost pressures across the Australian economy.
2:00 PM AEDT – Bank of Japan Interest Rate Decision: Investors will monitor the central bank's policy decision and guidance for indications of Japan's interest rate outlook and potential implications for global financial markets.
Summary
ASX 200 futures point to a positive opening, rising 32 points (+0.35%), as the US 10-year Treasury yield fell below 5%.
S&P 500 declined 0.30% to 7,720, while the Dow Jones fell 0.25% to 52,343.
Nasdaq Composite dropped 1.38% to 26,185 amid renewed selling pressure in technology stocks.
Alphabet shares plunged 12.6%, reflecting concerns over AI spending and weaker-than-expected search performance.
S&P 500 Equal Weight Index gained 1.2%, supported by healthcare, real estate and financial stocks.
Gold declined 1.14% to US$4,021.33 per ounce, while silver dropped 2.64% to US$52.25 per ounce.
WTI crude oil edged up 0.13% to US$102.92 per barrel, supported by ongoing geopolitical uncertainty.
Bitcoin declined 2.88% to US$78,926, while copper weakened 1.25% to US$6.56 per pound.
US 10-year Treasury yields eased to approximately 4.9%, while the ECB maintained its deposit rate at 2.50%.
US Q3 GDP expanded at an annualised 3.4%, while September PCE inflation reached 3.6% year-on-year.
Disclaimer for Kapitales Research
The materials provided by Kapitales Research, including articles, news, data, reports, opinions, images, charts, and videos ("Content"), are intended for personal, non-commercial use only. The primary goal of this Content is to educate and inform readers. This Content is not meant to offer financial advice, nor does it include any recommendation or opinion that should be relied upon for making financial decisions. Certain Content on this platform may be sponsored or unsponsored, but it does not serve as a solicitation or endorsement to buy, sell, or hold any securities, nor does it encourage any specific investment activities. Kapitales Research is not authorized to provide investment advice, and we strongly advise users to seek guidance from a qualified financial professional, such as a financial advisor or stockbroker, before making any investment choices. Kapitales Research disclaims all liability for any direct, indirect, incidental, or consequential damages arising from the use of the Content, which is provided without any warranties. The opinions expressed by contributors or guests are their own and do not necessarily reflect the views of Kapitales Research. Media such as images or music used on this platform are either owned by Kapitales Research, sourced through paid subscriptions, or believed to be in the public domain. We have made reasonable efforts to credit sources where appropriate. Kapitales Research does not claim ownership of any third-party media unless explicitly stated otherwise.
Customer Notice:
Nextgen Global Services Pty Ltd trading as Kapitales Research (ABN 89 652 632 561) is a Corporate Authorised Representative (CAR No. 1293674) of Enva Australia Pty Ltd (AFSL 424494). The information contained in this website is general information only. Any advice is general advice only. No consideration has been given or will be given to the individual investment objectives, financial situation or needs of any particular person. The decision to invest or trade and the method selected is a personal decision and involves an inherent level of risk, and you must undertake your own investigations and obtain your own advice regarding the suitability of this product for your circumstances. Please be aware that all trading activity is subject to both profit & loss and may not be suitable for you. The past performance of this product is not and should not be taken as an indication of future performance.
Disclosure: The information mentioned above has been sourced from the company reports and a third-party database, i.e. Koyfin. Investors are advised to use strict stop-loss to protect their investments in case of any unfavorable/uncertain market events.
Kapitales Research, Level 13, Suite 1A, 465 Victoria Ave, Chatswood, NSW 2067, Australia | 1800 005 780 | info@kapitales.com.au
We use cookies to help us improve, promote, and protect our services.
By continuing to use this site, we assume you consent to this.
Read our
Privacy Policy
and
Terms & Conditions
Markets Today (30 October 2026) at Open: Kapitales Morning Highlights from Wall Street to ASX
Headline
Global Markets Overview
Global equity markets delivered a mixed performance, reflecting divergent investor sentiment across major regions. In the United States, the S&P 500, Nasdaq Composite and Dow Jones Industrial Average closed lower, as selling pressure in technology stocks weighed on broader market sentiment. The Nasdaq experienced the sharpest decline among major US benchmarks, highlighting continued concerns surrounding technology valuations and corporate earnings. Meanwhile, European equities showed resilience, with the UK's FTSE 100 advancing despite ongoing economic uncertainty and shifting monetary policy expectations. Canada's S&P/TSX Composite finished marginally lower, indicating subdued investor participation.
Across Asian markets, Japan's Nikkei recorded solid gains, supported by positive investor sentiment and strength in domestic equities. Indian equities also advanced, reflecting improved market confidence and buying interest across key sectors. New Zealand's NZX 50 ended higher, indicating a relatively positive trading session. Overall, global markets demonstrated contrasting trends, with weakness in US technology shares offset by gains across selected European and Asian benchmarks, while investors continued assessing corporate earnings, economic developments and monetary policy expectations.
Commodities & Crypto
Commodity markets displayed a predominantly weaker trend, reflecting cautious investor sentiment amid global economic uncertainty and shifting monetary policy expectations. Gold prices declined amid selling pressure across precious metals. Silver experienced a sharper decline, highlighting broader selling pressure across precious metals. Meanwhile, copper prices weakened, reflecting concerns surrounding industrial demand and the outlook for global manufacturing activity. Uranium prices also declined, reflecting broader weakness across commodity markets. In contrast, West Texas Intermediate (WTI) crude oil edged higher, demonstrating relative resilience amid ongoing geopolitical uncertainty and supply-related considerations. In the cryptocurrency market, Bitcoin declined considerably, reflecting reduced appetite for speculative assets amid broader financial market volatility. Overall, commodity and cryptocurrency markets remained under pressure, with modest strength in crude oil providing a limited offset to widespread declines across metals and digital assets.
Bond Yields
Global government bond yields moved predominantly lower, with Australian and US yields declining, while Japanese yields edged higher amid diverging monetary policy expectations. Australian 10-year government bond yields declined, reflecting improved demand for fixed-income securities amid changing interest rate expectations. In contrast, Japan's 10-year government bond yield edged higher, indicating continued upward pressure on domestic borrowing costs. Meanwhile, US Treasury yields declined across longer maturities, with the 10-year yield falling below 5% and the 30-year yield also moving lower. Shifting expectations regarding the Federal Reserve's future interest rate decisions also influenced bond market sentiment. Overall, government bond yields moved predominantly lower, with Australian and US yields declining while Japanese yields edged higher, reflecting differences in regional monetary policy expectations and prevailing market conditions.
Key Drivers
ASX Company News
Stocks trading ex-dividend today
Key Economic Drivers (What to Watch Today)
Summary
Disclaimer for Kapitales Research
The materials provided by Kapitales Research, including articles, news, data, reports, opinions, images, charts, and videos ("Content"), are intended for personal, non-commercial use only. The primary goal of this Content is to educate and inform readers. This Content is not meant to offer financial advice, nor does it include any recommendation or opinion that should be relied upon for making financial decisions. Certain Content on this platform may be sponsored or unsponsored, but it does not serve as a solicitation or endorsement to buy, sell, or hold any securities, nor does it encourage any specific investment activities. Kapitales Research is not authorized to provide investment advice, and we strongly advise users to seek guidance from a qualified financial professional, such as a financial advisor or stockbroker, before making any investment choices. Kapitales Research disclaims all liability for any direct, indirect, incidental, or consequential damages arising from the use of the Content, which is provided without any warranties. The opinions expressed by contributors or guests are their own and do not necessarily reflect the views of Kapitales Research. Media such as images or music used on this platform are either owned by Kapitales Research, sourced through paid subscriptions, or believed to be in the public domain. We have made reasonable efforts to credit sources where appropriate. Kapitales Research does not claim ownership of any third-party media unless explicitly stated otherwise.
Customer Notice:
Nextgen Global Services Pty Ltd trading as Kapitales Research (ABN 89 652 632 561) is a Corporate Authorised Representative (CAR No. 1293674) of Enva Australia Pty Ltd (AFSL 424494). The information contained in this website is general information only. Any advice is general advice only. No consideration has been given or will be given to the individual investment objectives, financial situation or needs of any particular person. The decision to invest or trade and the method selected is a personal decision and involves an inherent level of risk, and you must undertake your own investigations and obtain your own advice regarding the suitability of this product for your circumstances. Please be aware that all trading activity is subject to both profit & loss and may not be suitable for you. The past performance of this product is not and should not be taken as an indication of future performance.
Disclosure: The information mentioned above has been sourced from the company reports and a third-party database, i.e. Koyfin. Investors are advised to use strict stop-loss to protect their investments in case of any unfavorable/uncertain market events.
Kapitales Research, Level 13, Suite 1A, 465 Victoria Ave, Chatswood, NSW 2067, Australia | 1800 005 780 | info@kapitales.com.au