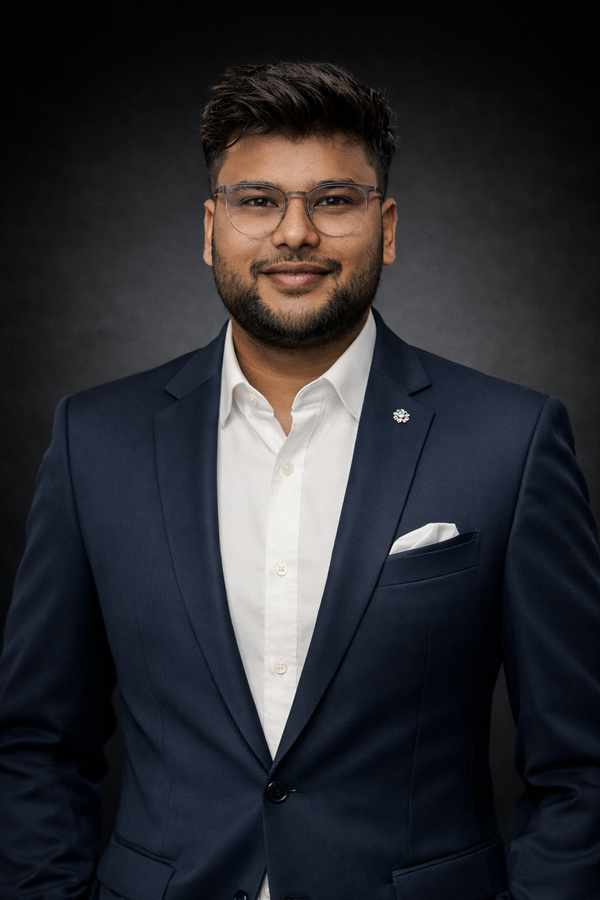
Mayank Bansal, CFA
Mayank Bansal is a CFA Charterholder and heads the Equity Research team at Kapitales Research, with over 5 years of experience analysing global equity markets. He leads fundamental, data-driven research combining rigorous financial analysis with macro trends.
Kapitales Morning Highlights from Wall Street to ASX - 3 November 2026
Headline
Global Markets Overview
Global equity markets delivered a mixed performance as investors assessed geopolitical developments, corporate earnings and shifting expectations for monetary policy. In the United States, the S&P 500 and Nasdaq Composite closed lower as renewed selling pressure in technology stocks weighed on broader market sentiment. However, the Dow Jones Industrial Average advanced, supported by gains in cyclical and traditional industrial sectors. European markets remained relatively resilient, with the UK's FTSE 100 finishing higher amid selective buying across major sectors. Canada's S&P/TSX Composite also strengthened, reflecting positive sentiment in parts of the domestic equity market.
In the Asia-Pacific region, Japan's Nikkei declined as investors remained cautious about economic conditions and corporate earnings prospects. Meanwhile, India's equity market recorded a strong advance, outperforming several major global benchmarks amid improved investor confidence. New Zealand's NZX 50 ended lower, indicating subdued sentiment in the domestic market. Overall, global equity markets ended mixed, with benchmarks in the United Kingdom, Canada and India advancing, while Japan and New Zealand recorded losses. US markets also diverged, as the Dow Jones gained while the S&P 500 and Nasdaq Composite declined.
Commodities & Crypto
Commodity markets recorded mixed movements, with precious metals strengthening while crude oil experienced significant selling pressure. Gold advanced as investors-maintained interest in safe-haven assets amid geopolitical and economic uncertainty. Silver also gained, reflecting broader strength across precious metals. Meanwhile, WTI crude oil declined sharply as optimism surrounding potential diplomatic progress between the United States and Iran eased concerns over supply disruptions. Uranium prices declined, reflecting weaker market sentiment.
Copper prices moved higher, indicating resilience in industrial metals despite uncertainty surrounding global demand. Bitcoin declined, reflecting subdued sentiment across cryptocurrency markets. Overall, commodity markets delivered mixed performances, with gains in gold, silver and copper contrasting with declines in crude oil and uranium, while Bitcoin also faced selling pressure.
Bond Yields
Government bond yields moved predominantly lower across major markets, with Australia and the United States recording declines, while Japan registered a marginal increase. Australia's 10-year government bond yield eased to 5.134%, indicating a modest decline in longer-term borrowing costs. In contrast, Japan's 10-year government bond yield edged higher to 2.767%, reflecting a slight upward movement in domestic yields. Meanwhile, US Treasury yields declined across longer maturities, with the benchmark 10-year yield falling to 4.911% and the 30-year yield retreating to 5.287%. Overall, bond market movements were relatively modest, with downward pressure on Australian and US yields contrasting with a slight increase in Japan.
Key Drivers
ASX Company News
Stocks trading ex-dividend today
Key Economic Drivers (What to Watch Today)
Summary
Disclaimer for Kapitales Research
The materials provided by Kapitales Research, including articles, news, data, reports, opinions, images, charts, and videos ("Content"), are intended for personal, non-commercial use only. The primary goal of this Content is to educate and inform readers. This Content is not meant to offer financial advice, nor does it include any recommendation or opinion that should be relied upon for making financial decisions. Certain Content on this platform may be sponsored or unsponsored, but it does not serve as a solicitation or endorsement to buy, sell, or hold any securities, nor does it encourage any specific investment activities. Kapitales Research is not authorized to provide investment advice, and we strongly advise users to seek guidance from a qualified financial professional, such as a financial advisor or stockbroker, before making any investment choices. Kapitales Research disclaims all liability for any direct, indirect, incidental, or consequential damages arising from the use of the Content, which is provided without any warranties. The opinions expressed by contributors or guests are their own and do not necessarily reflect the views of Kapitales Research. Media such as images or music used on this platform are either owned by Kapitales Research, sourced through paid subscriptions, or believed to be in the public domain. We have made reasonable efforts to credit sources where appropriate. Kapitales Research does not claim ownership of any third-party media unless explicitly stated otherwise.
Customer Notice:
Nextgen Global Services Pty Ltd trading as Kapitales Research (ABN 89 652 632 561) is a Corporate Authorised Representative (CAR No. 1293674) of Enva Australia Pty Ltd (AFSL 424494). The information contained in this website is general information only. Any advice is general advice only. No consideration has been given or will be given to the individual investment objectives, financial situation or needs of any particular person. The decision to invest or trade and the method selected is a personal decision and involves an inherent level of risk, and you must undertake your own investigations and obtain your own advice regarding the suitability of this product for your circumstances. Please be aware that all trading activity is subject to both profit & loss and may not be suitable for you. The past performance of this product is not and should not be taken as an indication of future performance.
Disclosure: The information mentioned above has been sourced from the company reports and a third-party database, i.e. Koyfin. Investors are advised to use strict stop-loss to protect their investments in case of any unfavorable/uncertain market events.
Kapitales Research, Level 13, Suite 1A, 465 Victoria Ave, Chatswood, NSW 2067, Australia | 1800 005 780 | info@kapitales.com.au